
An offer has been accepted. The purchase price has been discussed, and both parties are interested in moving forward with the transaction.
At this stage, it may seem that the most significant part of the deal has already been agreed upon. However, there are still important details to work through before ownership can officially change hands.
How will the payment be structured? What happens if certain conditions are not fulfilled? What assurances must the seller provide about the business? And are there any responsibilities that either party will need to fulfil after the transaction is completed?
These are among the matters that need to be clearly discussed and agreed upon as the transaction progresses. They are typically addressed in a key legal document known as the Share Purchase Agreement (SPA).
For SME business owners, understanding the SPA is important because it governs much more than the transfer of shares itself. Its terms can have practical implications for both the buyer and seller, before and after the transaction is completed.
What Is a Share Purchase Agreement in M&A?
An SPA is a legally binding contract between the seller and buyer that governs the sale and purchase of shares in a company.
In a share acquisition, the buyer acquires shares from the existing shareholders, thereby obtaining ownership of the company. The company itself remains the same legal entity, retaining its existing assets, contracts, employees and obligations, subject to the terms of the transaction and applicable laws.
This differs from an asset acquisition, where the buyer purchases specific assets or business operations rather than acquiring shares in the company. The structure chosen will influence what is transferred and the legal, financial and commercial considerations that need to be addressed.
Therefore, an SPA is an important document in a M&A transaction, as it formalises the terms agreed between the buyer and seller and translates them into legally enforceable obligations. It sets out key matters such as what is being sold, how the purchase price will be determined and paid, what each party is required to do, and what happens if certain conditions are not met.
How Due Diligence Shapes the SPA
Due diligence typically takes place before the SPA is finalised, allowing the buyer to review the target company and identify matters that may need to be addressed in the agreement.
The process involves a detailed review of areas such as the target company’s financial position, business operations, legal matters, tax affairs, material contracts, employees and other relevant information. We explore the due diligence process in more detail in another article covering the core areas that every SME business owner should know.
The findings from due diligence can then help shape the terms of the SPA, including:
• The purchase price and payment structure
• Representations and warranties
• Indemnities
• Conditions that must be fulfilled before completion
• Specific actions required from either party
• Other contractual protections or adjustments
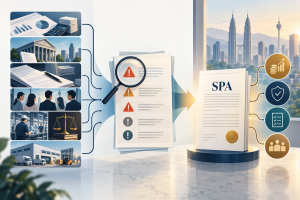
For example, if due diligence identifies a particular tax, legal or commercial concern, the parties may need to agree on how it should be addressed. This could involve further disclosure by the seller, a specific indemnity, an adjustment to the transaction terms or an agreed action before completion.
An M&A adviser can help coordinate the due diligence process, facilitate communication between the parties and ensure that important commercial findings are reflected in the transaction discussions. Legal advisers and other professional specialists provide the relevant technical advice and translate the agreed arrangements into the appropriate legal documents.
Ultimately, what is identified during due diligence can shape the terms that are negotiated and ultimately reflected in the SPA.
What Does a Share Purchase Agreement Cover?
The contents of an SPA will vary depending on the nature, size and complexity of the transaction. However, several key terms are commonly addressed.
1. Shares Being Acquired
The SPA identifies the shares being sold and purchased, including the number or percentage of shares involved in the transaction.
This is important because the scope of the acquisition determines the extent of ownership and control being transferred to the buyer. The agreement should clearly establish whether the buyer is acquiring the entire shareholding or only a portion of the company.
Where only part of the company is being acquired, the parties may also need to consider the rights and responsibilities of the remaining shareholders, including matters relating to management, decision-making, dividend distribution and future share transfers.
In situations where the buyer and existing shareholders will continue to hold shares in the company together, such as in a majority, minority or step acquisition, a Shareholders’ Agreement (SHA) is typically put in place. While the SPA governs the sale and purchase of the shares, the SHA sets out how the shareholders will manage their ongoing relationship, including their respective rights and responsibilities in the company.
2. Purchase Price and Payment Structure
The purchase price is naturally one of the most closely negotiated aspects of an M&A transaction. However, the SPA needs to go beyond stating the agreed amount. It should also explain how and when the consideration will be paid.
Depending on the transaction, the payment structure may involve an upfront payment, deferred consideration, an earn-out linked to the company’s future performance, or adjustments based on the company’s financial position at completion.
For sellers, this means looking beyond the headline purchase price. The timing and certainty of payment, any performance conditions and potential adjustments can all affect the amount ultimately received. For buyers, the payment structure can help ensure that the consideration reflects the company’s financial position and the agreed basis of the transaction.
The SPA should therefore clearly set out the payment schedule, calculation methodology, relevant deadlines and procedures for resolving any disagreements over the amount payable.
3. Representations, Warranties and Indemnities
Representations and warranties are contractual statements made by the parties concerning specified matters relevant to the transaction.
In a share acquisition, the seller may provide warranties relating to the target company’s financial statements, ownership of assets, material contracts, employees, tax matters, litigation, intellectual property and compliance with applicable laws.
The scope of these warranties may be informed by the due diligence process and the matters identified during the review of the business. They provide the buyer with contractual protection if certain statements about the business later prove to be inaccurate, subject to the terms of the SPA.
Indemnities, on the other hand, generally require one party to compensate the other for specified losses and may be used to address specific risks or liabilities identified during due diligence or negotiations.
For sellers, both warranties and indemnities require careful consideration because they may create potential financial exposure after completion. Sellers should understand precisely what they are being asked to confirm, what matters need to be disclosed, and the circumstances in which they may be held responsible for losses.
The scope of these terms, including any financial limits, time restrictions and procedures for bringing claims, should therefore be carefully considered and negotiated with the parties’ legal advisers.
4. Conditions Precedent
Conditions precedent are requirements that must be fulfilled, or waived where permitted, before the transaction can proceed to completion.
These may include obtaining regulatory or governmental approvals, securing consent from relevant third parties, obtaining necessary shareholder or board approvals, and completing agreed corporate actions.
The SPA should specify the conditions that must be satisfied, who is responsible for fulfilling them, the relevant timeframe, and what happens if any of the requirements cannot be met. These conditions can also be particularly important in cross-border transactions, where regulatory requirements and necessary approvals may differ across jurisdictions.
5. Completion and Post-Completion Obligations
Completion, sometimes referred to as closing, is the stage at which the agreed transaction is formally carried out.
The SPA sets out the actions required from both parties at completion. These may include payment of the purchase price, execution and delivery of share transfer documents, delivery of relevant corporate records, and completion of other agreed formalities.
However, not all responsibilities end once the shares have been transferred and the purchase price has been paid. Depending on the transaction, the SPA may include certain obligations that continue after completion, including transitional assistance, confidentiality, non-competition, non-solicitation, further documentation or other matters agreed between the parties.
Such terms can be particularly relevant where the seller has played a significant role in the company’s operations, customer relationships or management. Following the acquisition, selling shareholders or founders will typically be asked to remain involved in the company for a transition period to support the handover of the business, whether in a director, management or advisory role. Where this is the case, they will typically also be required to sign a separate Service Agreement (SA), which sets out the terms of their continued involvement, including their role, responsibilities and other arrangements during the transition period.
Clear completion and post-completion terms help establish expectations for the ownership transition and support a more orderly handover.
Additional Considerations in Cross-Border M&A
In cross-border M&A transactions, the SPA may involve additional considerations because the buyer and seller operate in different jurisdictions.
For example, when a Japanese company acquires a Malaysian business, both parties may need to navigate differences in legal and regulatory requirements, business practices, communication styles and expectations. Depending on the business nature and transaction structure, these differences may extend to foreign investment requirements, tax considerations, management arrangements and other transaction-specific matters.
Beyond the legal and regulatory aspects, the parties may also have different expectations regarding management involvement, employee arrangements, business continuity and the company’s future direction. These matters should be discussed early in the transaction process and, where relevant, reflected in the SPA or other transaction documents.
Having a professional M&A adviser who understands both the local business environment and the overseas buyer’s expectations can help bridge these differences. This can be particularly valuable in transactions between Malaysian business owners and Japanese strategic buyers, where clear communication and a shared understanding of the transaction objectives can support a smoother process.
What Should Business Owners Consider Before Signing an SPA?
Before signing an SPA, business owners should review the key terms carefully and understand what they mean in practice. Key areas to consider include:
• Transaction structure: Are the shares being sold and the percentage of ownership clearly stated?
• Purchase price and payment arrangement: Is the purchase price clearly defined, and are the payment arrangements and any adjustments understood?
• Representations and warranties: Are the statements being made accurate, and have all relevant matters been properly disclosed?
• Indemnities and liabilities: Are the potential responsibilities and financial exposures clearly understood?
• Conditions for completion: Are the necessary approvals, consents and other requirements clearly stated?
• Post-completion obligations: Are there any responsibilities, restrictions or transitional arrangements that will continue after the sale?
• Professional advice: Has the agreement been reviewed by qualified legal counsel, and do you understand the commercial implications of the agreed terms?
This checklist is not a substitute for a full legal review. Rather, it serves as a starting point for business owners to identify the matters they should understand and discuss with their professional advisers.
Understanding What You Are Agreeing To
An M&A transaction involves more than agreeing on the value of a business. The terms set out in the Share Purchase Agreement determine how ownership will be transferred, what each party is responsible for, and how risks and obligations will be managed before and after completion.
For business owners, the SPA should therefore be viewed as more than a legal formality. Taking the time to review its key terms, understand their practical implications and seek appropriate professional advice can support a more informed decision about the transaction.
Ultimately, signing an SPA means committing not only to the sale itself, but also to the terms that will govern how that sale is carried out.